


Special Report
2021 Inkjet Technology Trend for Display Report
₩5,000,000
October 22, 2021
Introduce
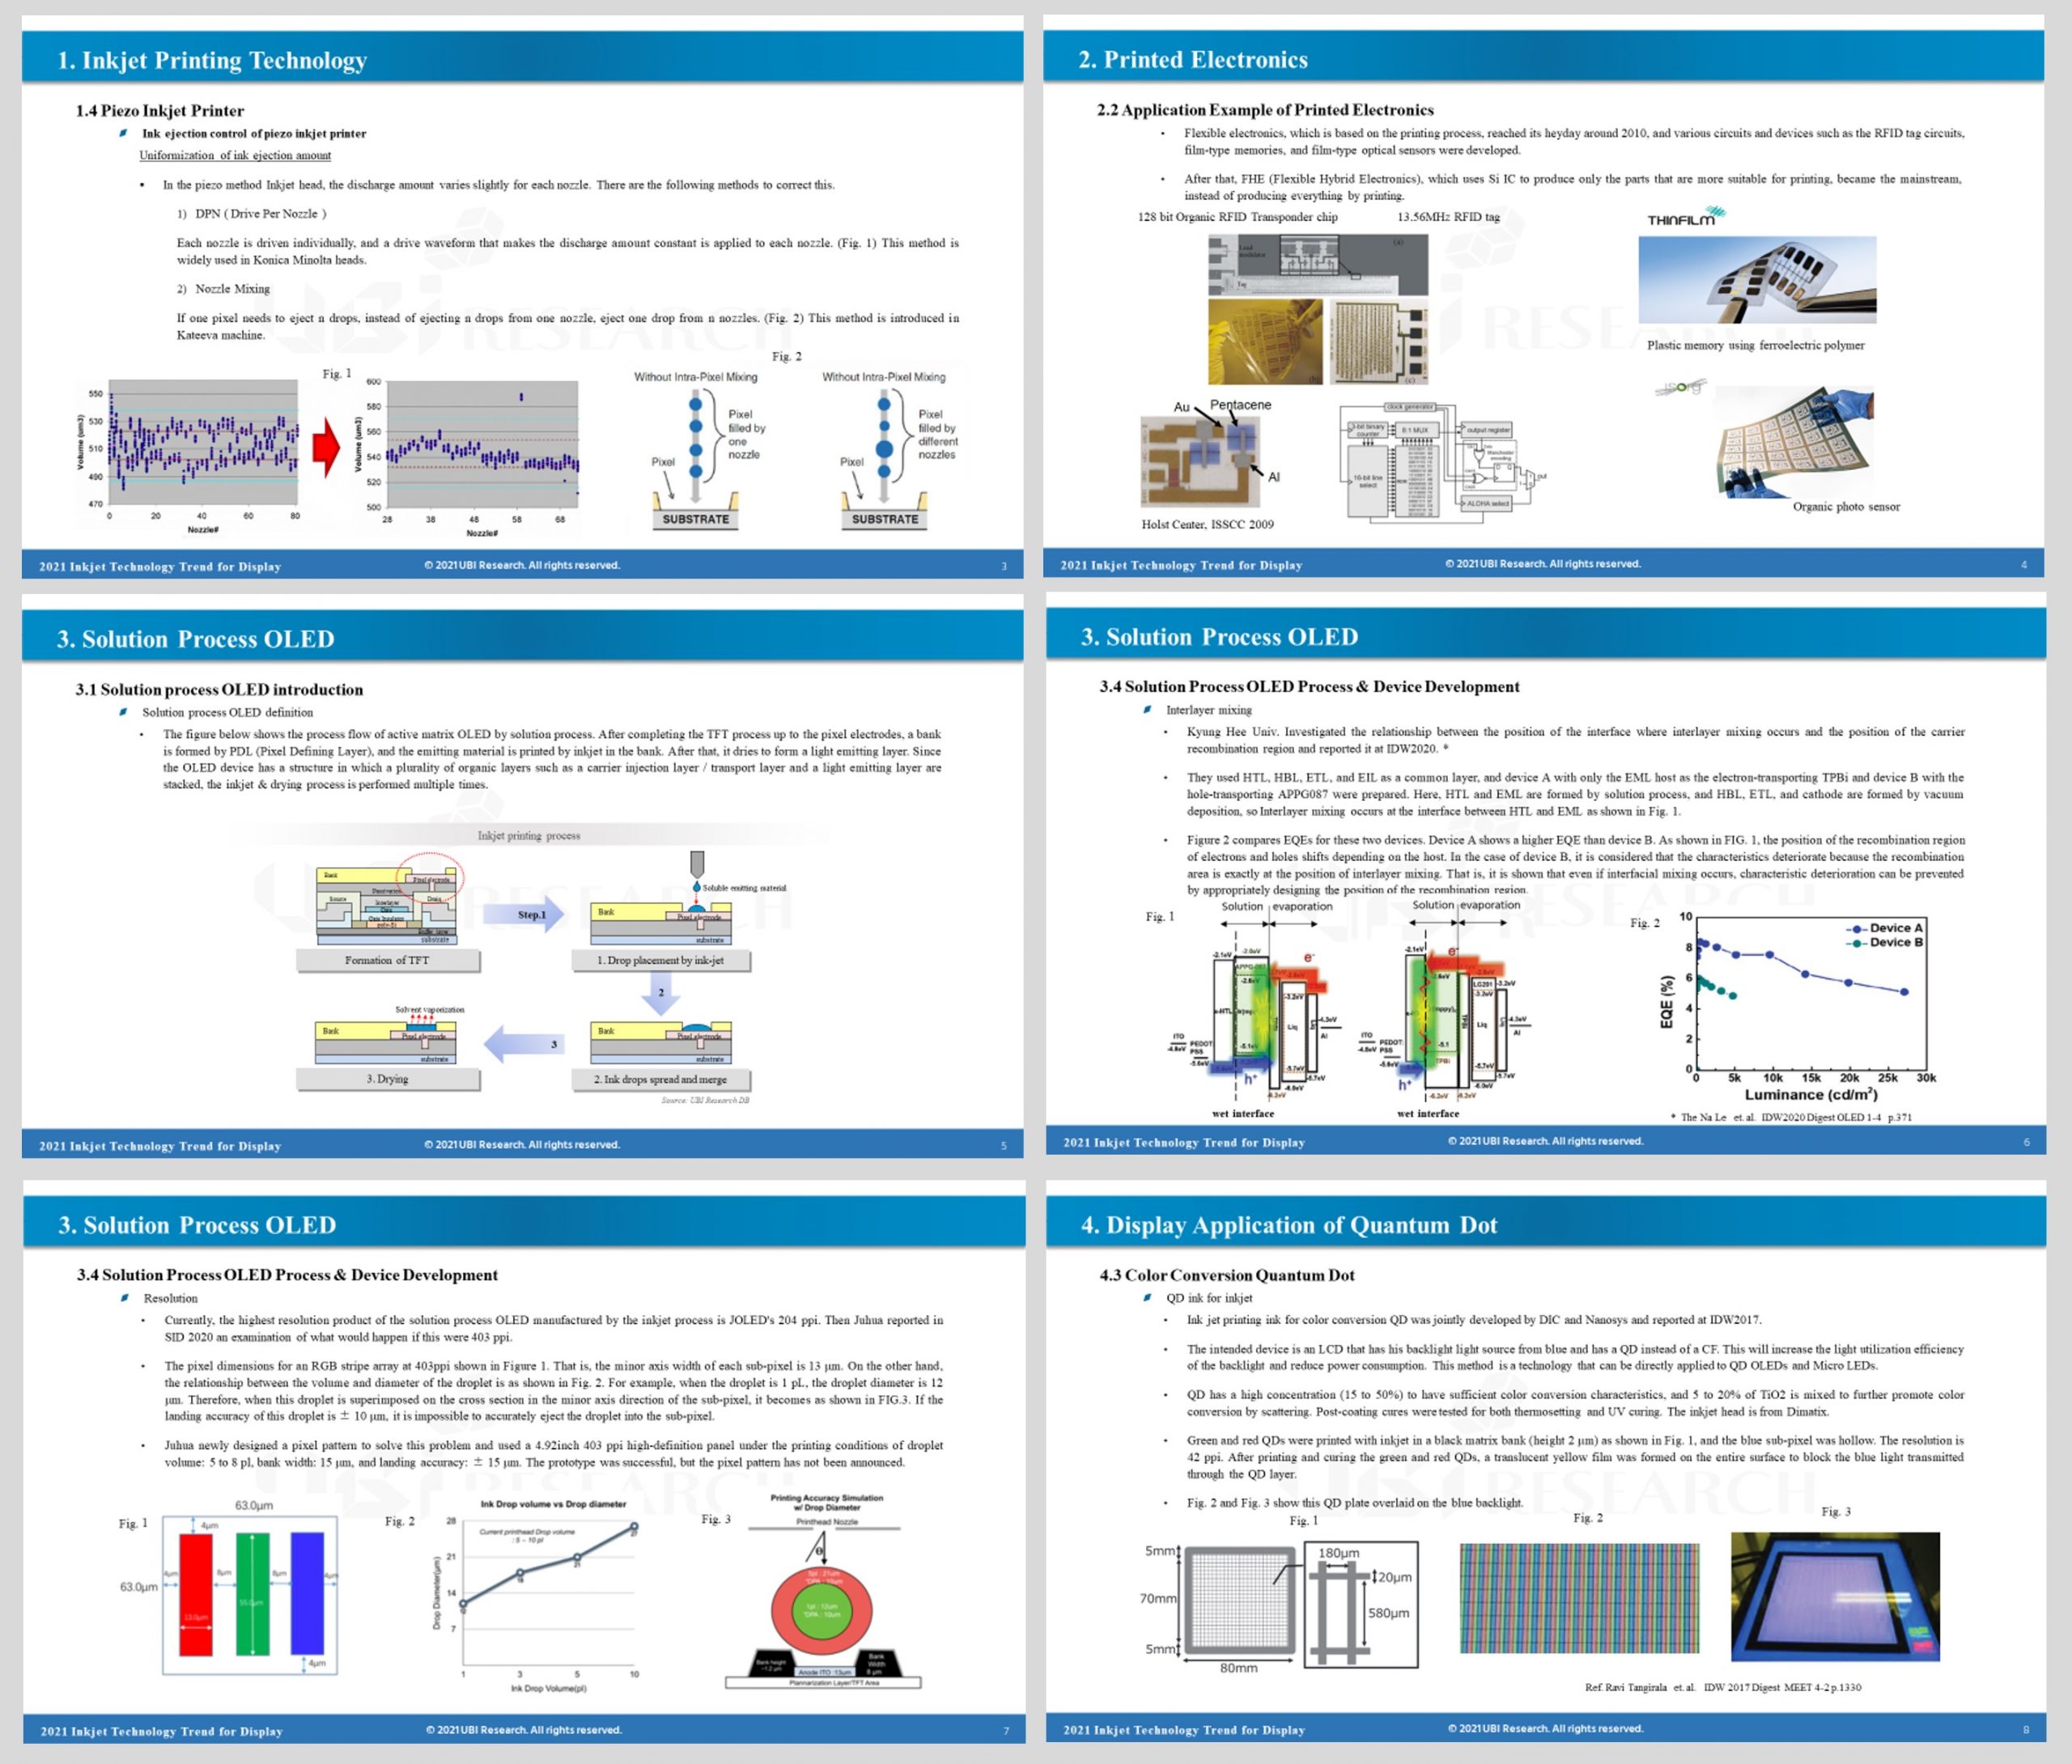
This report focuses on inkjet devices and technologies used in OLED and QLED. Inkjet equipment was created by separating the companies that manufacture inkjet heads and systems.
As inkjet head makers, Fujifilm Dimatix, Epson, Konica Minolta, Ricoh, Xaar, and Panasonic were mentioned, and OLED encapsulation equipment makers Kateeva and UniJet were described.
Litrex, TEL (Tokyo Electron), Kateeva, Panasonic Production Engineering, and Toray Engineering are mentioned as inkjet device manufacturers used for Sol OLED.
Contents
1. Inkjet Printing Technology
1.1 Printing Technology Classification
1.2 Inkjet Printing Technology Classification
1.3 Thermal Inkjet Printer
1.4 Piezo Inkjet Printer
1.5 Piezo Inkjet Head
1.6 Application of Inkjet Printing to Display
2. Printed Electronics
2.1 What is Printed Electronics?
2.2 Application Example of Printed Electronics
2.3 Materials for Printed Electronics
2.4 Inkjet Process in Printed Electronics
2.5 Printed Electronics Application Devices
3. Solution Process OLED
3.1 Introduction to Solution Process
3.2 Materials for Solution Process
3.3 Solution Process Inkjet equipment for OLED
3.4 Solution Process OLED Process & Device Development
3.5 Solution Process OLE Display Development
4. Display Application of Quantum Dot
4.1 What is Quantum Dot?
4.2 Positioning of Quantum Dot in Display
4.3 Color Conversion Quantum Dot
4.4 Emission Type Quantum Dot
5. Further Technological Development
5.1 Electro Hydrodynamic ( EHD ) Printing
5.2 Ultra High-Definition Inkjet: XTPL
5.3 Organic Vapor Jet Printing (OVJP)
Report Sample
Previous Report Status
Related Products
-
2019 Solution Process OLED Annual Report
₩5,000,000March 31, 2019
Solution process using inkjet OLED (sol OLED) has been developed mainly as a large OLED panel for TV, but recently began to attract attention in the monitor display market. The evaporation method with FMM that produces OLED for smartphones has a bending phenomenon of FMM. Thus, the substrate is used by dividing into two or four. Since smartphone-sized FMMs are used by attaching 10 to 15 sheets to the mask frame, the profitability is very low due to the small number of cells in the production of 20-inch or larger monitors.
-

2026 Automotive Display: Technology, Supply Chain & Market Outlook
₩0September 17, 2026
UBI Research’s newly published report, 2026 Automotive Display: Technology, Supply Chain & Market Outlook, provides an integrated analysis of the rapidly evolving automotive display industry, examining technologies, application areas, and supply chain changes driven by the expansion of software-defined vehicles (SDVs) and smart cockpits.
The automotive display market is expected to grow in overall shipments while shifting toward a higher proportion of high-value-added displays. Although LCD shipments are projected to decline slightly through 2030, Mini LED shipments are forecast to increase approximately 2.9-fold, from 8.78 million units in 2026 to 25.06 million units in 2030. OLED shipments are also expected to more than double over the same period, rising from 6.15 million to 12.99 million units. As a result, market competition is expected to shift from shipment volume expansion toward high-value-added technologies offering superior image quality, higher brightness, and larger screen sizes.
The report examines how automotive displays are expanding beyond information displays centered on clusters and center information displays (CIDs) into passenger displays, rear-seat entertainment (RSE), camera monitoring systems (CMS), head-up displays (HUD), and augmented reality head-up displays (AR-HUD). It explores the growing number, screen area, and performance requirements of displays resulting from the transition to SDVs and smart cockpits. The report also analyzes rising AR-HUD demand driven by advances in ADAS, together with the shift toward multiscreen and content-centered experiences resulting from the expansion of passenger HMI. In addition, it outlines how emerging form factors—including Shy Tech, transparent displays, and transformable displays—are becoming key elements in differentiating user experiences and vehicle interiors.
The scope of competition is also expanding from panels to modules and systems. The conventional structure, in which panel suppliers provide displays and Tier 1 suppliers handle system integration, is evolving toward joint design involving panel makers and Tier 1 suppliers from the early stages of development. The supply scope is also progressing from FOG to FIDM and FIDM Plus. As the integration of touch solutions, cover glass, PCBAs, sensors, and other components increases, Tier 1 suppliers are creating greater value through cockpit computing, HMI software, and system integration. The report analyzes these changes in the supply structure and the evolving roles of OEMs, Tier 1 suppliers, and panel makers.
It also compares the technological characteristics of TFT-LCD, Mini LED, OLED, and Micro LED with the performance requirements of automotive applications. In addition, it reviews the automotive display strategies and market outlooks of major panel manufacturers, including AUO, BOE, LG Display, Samsung Display, TCL CSOT, Tianma, and Visionox.
Rather than simply listing individual technologies and market data, the report presents an integrated analysis that connects the growth drivers of the automotive display market with product applications, technology selection, modularization, supply chain restructuring, and the business strategies of major companies. It enables readers to identify where the competitive landscape is shifting and where new sources of added value and business opportunities are emerging. The report also provides practical criteria to support market entry, product development, customer strategies, and supply chain planning for companies involved in panels, materials, components, equipment, and automotive electronics -

Analysis Report on Perovskite Materials: Industry and Application Technologies
₩0September 22, 2026
“Analysis Report on Perovskite Materials: Industry and Application Technologies” provides an in-depth analysis of perovskite materials, from crystal structure, key properties and stability challenges to their two major application areas, displays and solar cells, covering Mini-LED color conversion, in-pixel color conversion (In-Pixel CC), self-emissive PeLEDs and perovskite/silicon tandem solar cells (PSTSC). It also examines the supply chain by process, patent and certification trends, and the market outlook through 2035.